5 Red Flags in Your Remodeling Contract That Cost You Big
Before you sign, learn to spot the clauses that turn dream renovations into legal nightmares.
Reading a remodeling contract can feel like deciphering ancient hieroglyphs. Most homeowners skim the price, check the start date, and sign on the dotted line, hoping for the best. The honest truth is, contractors know this. That’s why some bury <span class=”riq-cursive-accent”>sneaky clauses</span> that shift risk, inflate costs, and turn minor hiccups into major disputes. We’ve audited thousands of bids, and these five red flags pop up constantly, costing homeowners thousands and leading to headaches, delays, and even lawsuits. Don’t let your renovation become a statistic.
Red Flag #1: The Backloaded Payment Schedule
Your contractor wants a big chunk of money upfront, then very little work gets done until the final payment? Red flag alert: this is one of the oldest tricks in the book. A fair payment schedule should mirror the work completed. It protects both you and the contractor. Too much money upfront leaves you vulnerable if the contractor walks off the job or drags their feet. Most homeowners don’t know this, but contractors often use upfront payments from one job to fund another, which can quickly lead to financial instability and abandoned projects if things go sideways.
54%
of homeowners cite high costs and fear of contractor issues as primary renovation barriers.
Source: Houzz 2024 Renovation Trends (2024)
The problem isn’t just about losing money; it’s about losing leverage. Once a contractor has a significant portion of your money without delivering equivalent value, your power to demand timely, quality work diminishes. We see payment schedules with more than 30% upfront for projects under $50,000 as a serious Contract Risk deduction. A balanced schedule spreads payments out, typically with an initial deposit (10-20%), then payments tied to clear milestones like foundation completion, rough-ins, drywall, and final walk-through. Never pay for work that hasn’t been substantially completed.
The contractor’s payment schedule reveals more about their solvency than their skill.
Fair Payment Schedule
- 10-20% deposit to start
- Payments tied to completed milestones (e.g., rough-in complete, drywall hung)
- Final 10-15% paid ONLY after final inspection and punch list complete
- Clear, measurable progress benchmarks
Red Flag Payment Schedule
- 30-50% deposit for projects under $50k
- Payments based on arbitrary dates, not completed work
- Final payment due before project is 100% finished or inspected
- Vague descriptions like ‘initial phase’ or ‘materials delivered’
What to ask: “Can you explain your payment schedule and how each payment aligns with specific, completed work phases? I’d like to tie payments to clearly defined milestones, not just dates or general ‘progress’.” Be prepared to negotiate this point aggressively. A good contractor will be transparent; a bad one will get defensive.
Red Flag #2: Vague Allowances & Material Specifications
This is a classic <span class=”riq-cursive-accent”>scope creep trap</span>. An ‘allowance’ is a placeholder in your budget for items like flooring, tile, light fixtures, or plumbing fixtures. If your contract simply says ‘plumbing allowance: $1,000,’ that sounds reasonable until you go to pick out your new kitchen faucet and discover most decent options start at $400, leaving you with just $600 for the sink, disposal, and installation hardware. Anything over the $1,000 allowance becomes a change order, and you pay the difference, plus the contractor’s markup.
Most homeowners don’t realize these vague allowances add an average of 10-15% to project costs through change orders. This is a huge hit to your Price Check score. Contractors benefit because they can quote a lower initial price to win the bid, then make up the difference (and more) on overages. You lose control over your budget and end up paying more for items you thought were included. It’s a key reason why {brand} focuses 30% of its Confidence Score on Scope Completeness.
Vague allowances are change orders waiting to happen, usually with a markup.
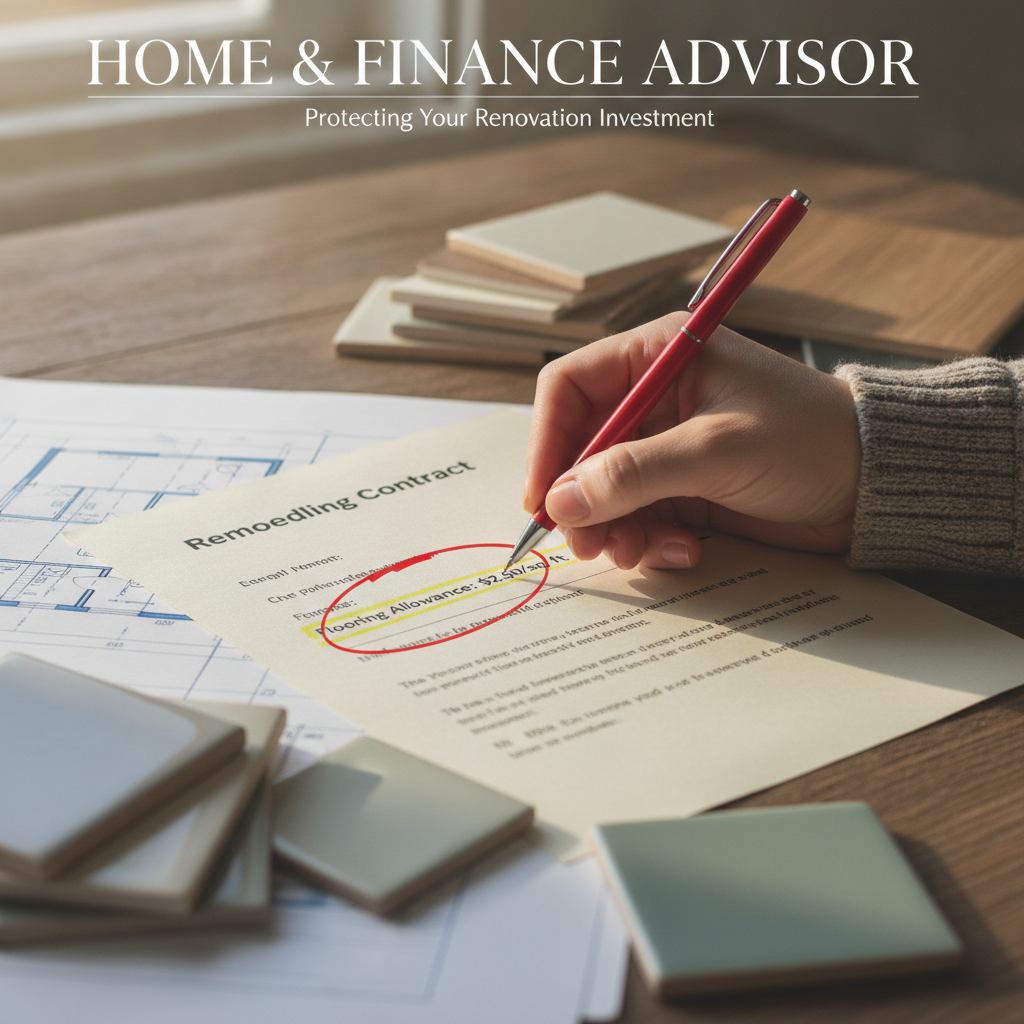
The language in your contract can cost you thousands. ‘Allowance’ is often code for ‘this will cost more.’ Don’t settle for broad terms. Get specific model numbers, grades, and unit costs.
What to ask: “For every allowance, I need specific material specifications or at least a ‘not to exceed’ price based on a specific product selection (e.g., ‘Kohler XYZ-123 kitchen faucet or equivalent, not to exceed $450’). What exact product or fixture is included in each allowance? If I choose something more expensive, what is the exact markup percentage on the difference?” Push for clear brand names, model numbers, and unit costs (per square foot, per fixture).
Red Flag #3: Missing or Improper Lien Waivers
You pay your contractor, but what if they don’t pay their subcontractors or material suppliers? Without a lien waiver, those unpaid parties can put a lien on your home, even though you’ve already paid the general contractor. A lien is a legal claim against your property, and it can prevent you from selling or refinancing your home until the debt is settled. It’s a huge Contract Risk and a major source of homeowner headaches.
80%
of mortgaged homeowners are ‘locked-in’ to rates below 5%, driving renovation demand.
Source: Redfin and Mortgage News Daily 2024 (2024)
The honest truth is, contractors sometimes struggle with cash flow. They might use your payment to cover another project’s expenses. Lien waivers protect you by proving that the subs and suppliers have been paid for the work on your specific project. You should receive a signed lien waiver from the general contractor and all major subcontractors and material suppliers *every time* you make a payment. Don’t make the next payment until you have waivers for the previous one.
Partial Lien Waiver
For progress payments. Waives rights for work done up to a certain date or amount.
Conditional Lien Waiver
Becomes effective *only* when payment clears. Good for checks that might bounce.
Unconditional Lien Waiver
Effective immediately upon signing, regardless of whether payment has cleared. Use with caution, usually for final payments where you’ve verified funds.
What to ask: “I need a signed lien waiver from all subcontractors and major material suppliers for the amount of work completed (or materials supplied) for this payment phase. What is your process for collecting and providing these with each payment?” Make sure your contract explicitly states that you will receive these waivers with each payment.
Red Flag #4: Vague Change Order Procedures
Even the best-planned renovations hit unexpected snags. Maybe you uncover old knob-and-tube wiring, or decide you want to add recessed lighting after all. These are ‘change orders’ — modifications to the original scope of work. A vague change order clause is a major Contract Risk because it allows contractors to tack on costs without proper justification or agreement, making it a <span class=”riq-cursive-accent”>blank check trap</span>.
A good contract clearly defines the process: a written change order, signed by both parties, detailing the new work, its cost, and any impact on the schedule. Without this, a verbal ‘sure, we can do that’ can turn into thousands of dollars in extra charges. We’ve seen homeowners hit with 20-30% cost increases solely from poorly managed change orders. This significantly impacts the Price Check component of your RemodelerIQ Confidence Score.
What to ask: “What is your exact process for change orders? I require all changes to be documented in writing, signed by both of us, and include a detailed breakdown of labor, materials, and any impact on the project schedule, before any new work begins.” Insist on this. It’s your right to know exactly what you’re paying for.
$85.34
National average hourly wage for a general contractor in 2026, plus 30-45% burden.
Source: BLS OEWS 2026 & RemodelerIQ 2026 Labor Rates (2026)
Red Flag #5: Missing or Incomplete Insurance Certificates
Your contractor tells you they’re insured. Great! But seeing is believing. A contractor without proper insurance — specifically General Liability and Workers’ Compensation — is a massive red flag. If a worker gets injured on your property, or damage occurs to your home or a neighbor’s property, you could be held liable. This is a risk no homeowner should ever take. The lock-in effect means more homeowners are improving in place, making proper contractor vetting even more critical.
Most homeowners don’t know this, but simply asking for a Certificate of Insurance isn’t enough. You need to verify it. Some contractors carry expired policies or even fake certificates. Always call the insurance company directly using the number on the certificate to confirm the policy is current and covers the scope of work for your project. Workers’ Compensation is particularly critical; without it, an injured worker could sue you directly, not just the contractor.
Never take an insurance certificate at face value. Call the provider directly. Every time.
What to ask: “Please provide current Certificates of Insurance for both General Liability (naming me as an additional insured) and Workers’ Compensation. I will be calling the providers to verify coverage. Can you also confirm the minimum coverage amounts for both policies?” Do not let anyone start work without verified, active insurance.
Protect Your Investment
Frequently Asked Questions
What’s the riskiest contract clause for a homeowner?
Vague allowances and poorly defined change order procedures are often the riskiest, as they directly lead to unexpected cost increases. Without clear specs, contractors can easily inflate prices for ‘upgrades’ you didn’t anticipate.
Should I pay a contractor 50% upfront?
No, rarely. For most residential projects, a deposit of 10-20% is standard. Any more than 30% upfront (especially for projects under $50,000) is a major red flag. Payments should be tied to completed work milestones, not just the start date.
How can RemodelerIQ help me avoid these red flags?
RemodelerIQ’s Three Pillars analyzer scrutinizes your contract for these exact risks. Our Contract Risk pillar identifies problematic clauses, while Price Check flags inflated costs from vague allowances, and Scope Completeness ensures all details are covered, giving you a Confidence Score before you sign.
What if my contractor refuses to provide lien waivers?
This is a serious red flag. If a contractor refuses to provide lien waivers for payments, do not make further payments. This is a crucial protection against future liens on your home by unpaid subcontractors or suppliers. Consider consulting a lawyer if the contractor is uncooperative.
My contractor just verbally told me about a change. Is that okay?
No, it’s not okay. Always insist on written, signed change orders that detail the scope, cost, and schedule impact. Verbal agreements are almost impossible to enforce and are a common cause of disputes and unexpected charges.
Leave a Reply